 Whether you are updating an older Texas home, adding square footage, or planning a full remodel, financing your project matters as much as choosing the right contractor. The good news is you have several loan options — and each fits a different kind of project and homeowner situation.
This guide walks through the main renovation loan choices available to Texas homeowners in 2026, how they differ, and how to pick the one that fits.
Why a Renovation Loan Instead of a Personal Loan or Credit Card?
Renovation loans are secured by the home, which generally means longer terms, lower monthly payments, and access to larger loan amounts than an unsecured personal loan or credit card. For a project that meaningfully improves the property, a renovation loan can be a smarter long-term financing choice.
The trade-off is that renovation loans require more paperwork, appraisals, and often contractor documentation. That extra process exists because you are borrowing against your home, and the lender needs to verify the project makes sense.
Renovation Loan Options for Texas Homeowners
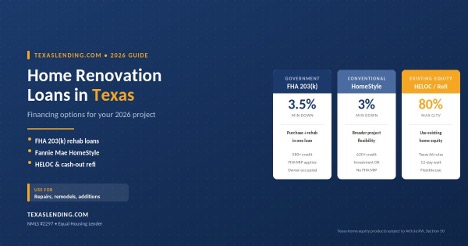
FHA 203(k) Rehab Loan
The FHA 203(k) is a government-backed loan designed to let buyers or homeowners finance both a home purchase (or refinance) and needed repairs or improvements in a single loan. There are two versions — a Limited 203(k) for smaller cosmetic and repair projects, and a Standard 203(k) for larger structural work.
Best for: buyers purchasing a fixer-upper, or homeowners needing to fund essential repairs.
Fannie Mae HomeStyle Renovation
HomeStyle is the conventional counterpart to the FHA 203(k). It rolls a purchase or refinance and renovation costs into one conventional mortgage, and it accepts a broader range of project types — including luxury improvements and investment properties.
Best for: homeowners with stronger credit who want flexibility on project scope. Can be used on investment properties.
→ Home Equity Loans in Texas — See how a fixed home equity loan compares as a renovation funding source.
HELOC or Home Equity Loan
If you already own your home and have built up equity, a HELOC or home equity loan can fund renovations without touching your first mortgage. A HELOC offers flexible access over time, while a home equity loan gives you a lump sum with fixed payments.
Best for: homeowners with existing equity who want to keep their current mortgage rate. Subject to Texas Constitution Article XVI, Section 50 — including the 80% combined loan-to-value cap and 12-day cooling-off period.
Cash-Out Refinance
A cash-out refinance replaces your existing mortgage with a larger one, giving you the difference in cash to use for the renovation. Because it replaces your mortgage, timing matters — this option makes the most sense when the new loan terms are competitive with what you already have.
Best for: homeowners with significant equity who are open to resetting their mortgage. Subject to Texas A6 rules for cash-out refinances.
→ Maximize Your Home Equity — Strategies for making smart use of existing home equity in Texas.
How to Choose the Right Renovation Loan
The right loan depends on three things: whether you already own the home, how much equity you have, and the scope of the project.
• Buying a fixer-upper? — FHA 203(k) or HomeStyle lets you buy and renovate with one loan.
• Own the home, need flexible access? — A HELOC lets you draw as project phases come up.
• Own the home, know the exact budget? — A home equity loan or cash-out refi gives you the full amount up front.
• Have low equity but strong credit? — HomeStyle refinance may be a better fit than tapping equity.
• Renovating an investment property? — HomeStyle is one of the few options that allows this.
A licensed mortgage consultant at Texaslending can walk through your specific situation and help you compare the total cost of each option.
What Renovations Add the Most Value?
Cost recovery on renovation projects varies widely by project type and market. National remodeling data consistently shows that curb-appeal projects — garage doors, siding, entry doors, and minor kitchen updates — tend to recover a higher percentage of their cost at resale than large-scale luxury additions.
In Texas specifically, weather-related improvements can also pay off — updates to roofing, HVAC, and insulation both improve the home’s function and can reduce insurance costs over time.
→ How Much House Can You Afford in Texas? — See how a renovation loan fits within your overall borrowing capacity.
Ready to Finance Your Renovation?
Every project is different, and the right loan depends on your goals, timeline, and equity position. The TexasLending team can walk through the options with you and help you compare what each one would look like at current mortgage rates.
→ Get Started with TexasLending.com ←
Want to run some scenarios first? Try our home purchase and payment calculators.


