 A Texas home equity loan can be one of the most useful financial tools available to homeowners — but qualifying takes more than just having equity in your home. Lenders look at several factors to determine whether your loan makes sense, and Texas has additional state-specific rules that shape what’s possible.
This guide breaks down the three main qualification factors, the Texas Constitution rules that apply, and what you can do to strengthen your application.
The Three Main Qualification Factors
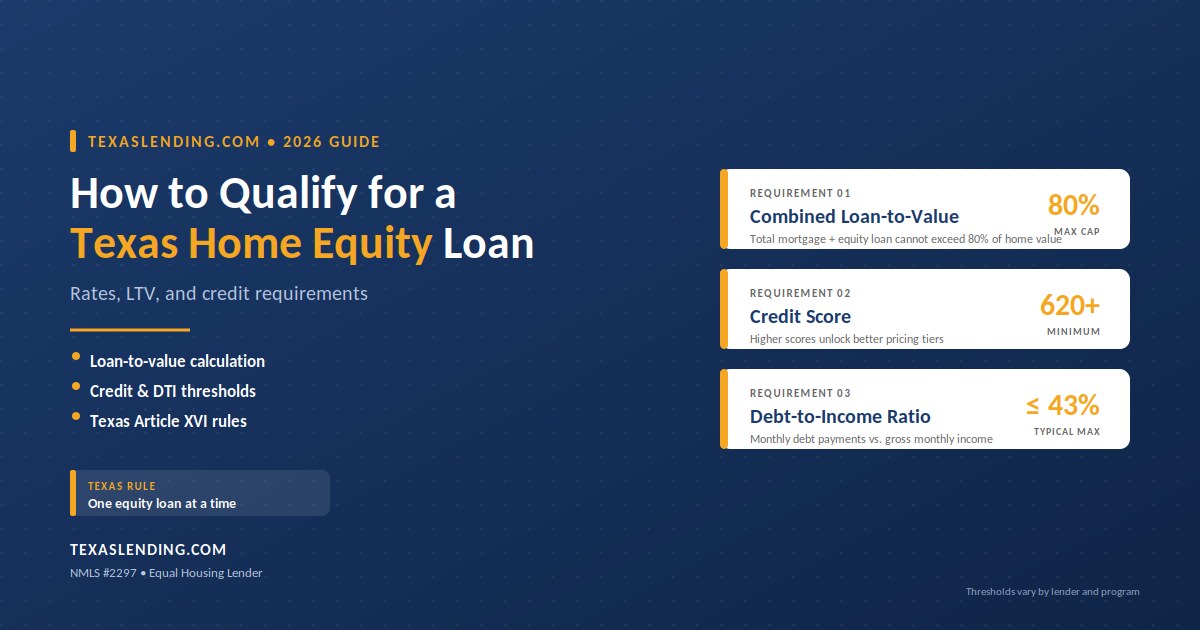
Most Texas lenders look at three primary factors when reviewing a home equity loan application: your loan-to-value ratio, your credit profile, and your debt-to-income ratio.
1. Combined Loan-to-Value (CLTV) — Capped at 80% in Texas
The most important number in a Texas home equity loan is your combined loan-to-value. This is the total of your first mortgage balance plus the new home equity loan, divided by your home’s appraised value.
Texas law caps CLTV on home equity products at 80%. That means if your home appraises for a given value, all the mortgages secured by your home — combined — cannot exceed 80% of that value. This is one of the strongest consumer protections in the country for home equity borrowers.
2. Credit Score — 620 Minimum, Higher Is Better
Most Texas lenders require a minimum credit score of 620 for home equity loans, though this varies by lender and program. Higher scores unlock better pricing tiers. Borrowers with scores in the 700+ range typically see the most competitive terms.
If your score is close to a tier threshold, waiting a few months to improve it — by paying down revolving balances or disputing errors — can meaningfully affect your loan terms.
3. Debt-to-Income Ratio — Typically 43% or Lower
Your debt-to-income ratio (DTI) compares your total monthly debt payments to your gross monthly income. Most lenders look for a DTI of 43% or lower, though some programs allow higher ratios for stronger borrowers.
Lenders calculate DTI using the new home equity loan payment — not your current one — so the loan you are applying for is factored into whether you qualify.
→ Home Equity Loans in Texas — See how home equity loans work and how they differ from cash-out refinancing.
Texas Constitution Rules That Affect Qualification
Beyond standard lender qualification, Texas has state-specific rules that shape home equity lending. These come from Article XVI, Section 50 of the Texas Constitution — commonly referred to as the A6 rules.
• 80% CLTV cap — Combined loan-to-value cannot exceed 80% of your home’s appraised value.
• One home equity loan at a time — You can only have one open home equity product secured by your homestead. This is often called the “once a Texas cash-out, always a Texas cash-out” rule.
• 12-day cooling-off period — At least 12 days must pass between application and closing.
• Homestead requirement — The property must be your primary residence to qualify for a home equity loan under Texas A6 rules.
• In-person closing required — Closing must take place at a title company, lender’s office, or attorney’s office.
• Fee cap — Lender fees on the home equity loan are limited by state law.
These rules add some time and paperwork to the process, but they also give Texas homeowners protections that most other states do not offer.
How to Strengthen Your Application
If your numbers are close to any of the qualification thresholds, small changes can meaningfully improve your loan terms.
• Pay down revolving debt — Reducing credit card balances lowers your DTI and often improves your credit score at the same time.
• Avoid new credit inquiries — In the months before applying, avoid opening new credit cards or financing large purchases.
• Check your credit report — Pull your report early and dispute any inaccuracies that could be dragging your score down.
• Wait for the equity to build — If your CLTV is close to 80%, waiting a few months for home values to move or paying down your first mortgage can help.
• Gather documentation early — Recent pay stubs, tax returns, W-2s, and bank statements are all needed. Having them ready speeds up the process.
→ Consolidate Credit Card Debt with a Cash-Out Refinance — Compare home equity loans to cash-out refinance for debt consolidation.
How Texas Home Equity Loan Rates Are Set
At current mortgage rates, your specific home equity loan rate depends on the same borrower-profile factors that shape any mortgage: your credit score, your LTV, your DTI, and the loan program you choose. Loan term length and property type also play a role.
The best way to see where you stand is to request a custom quote based on your actual numbers. Rate ranges you see advertised are usually for the strongest borrower profile — the number you personally receive is built specifically for your situation.
→ How to Get a Custom Rate Quote in Texas — See how each qualification factor is applied to your specific quote.
Ready to See What You Qualify For?
The best way to know where you stand is to talk with a licensed mortgage consultant. TexasLending has been helping Texas homeowners navigate home equity decisions for more than 25 years — and we can walk you through your specific numbers.
→ Get Started with TexasLending.com ←
Want to run scenarios first?


